The regulator is reviewing the case to determine responsibility for procedural irregularities and said appropriate action would be taken if violations are established.
How the IPO approval process works
Companies seeking to raise funds through an IPO must disclose their financial position, business plans and risks in a prospectus to help investors make informed decisions.
Under the process outlined by the SECP, companies are responsible for maintaining accurate financial records and providing complete business disclosures, while external auditors audit their financial statements.
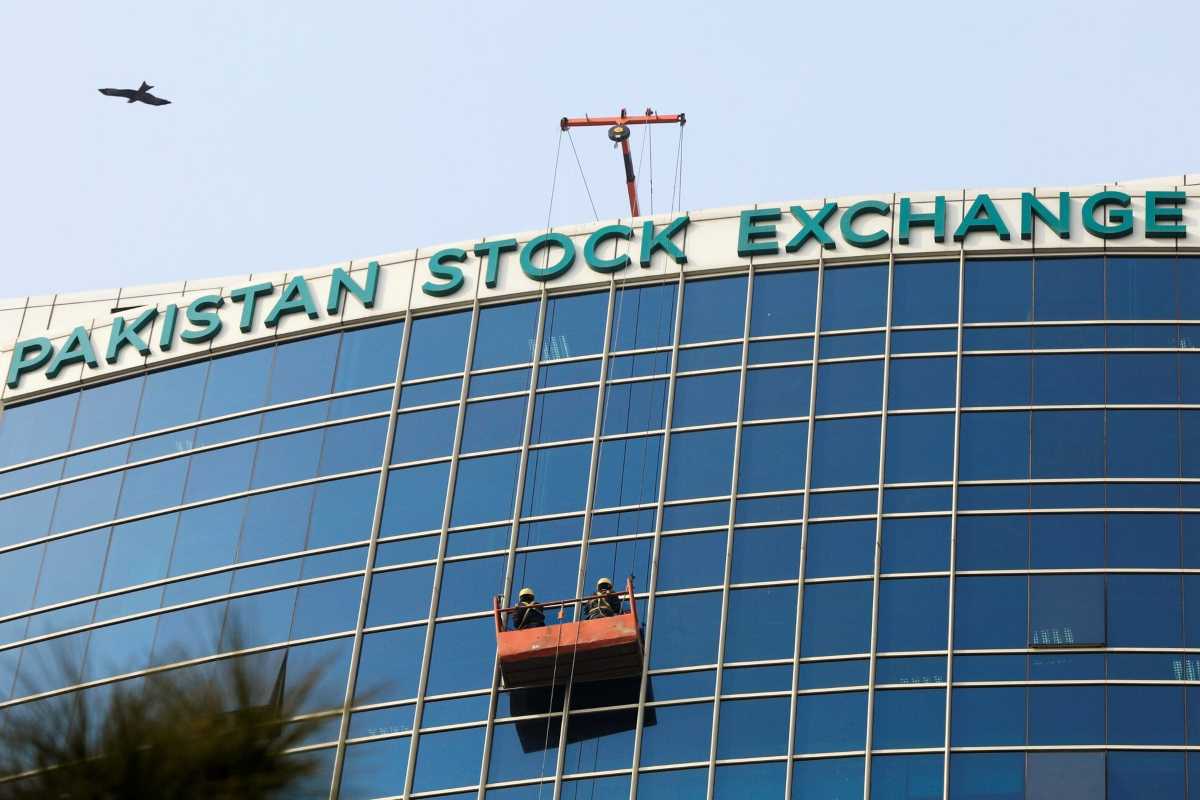
The consultant to the issue conducts due diligence, prepares the draft prospectus and submits applications to the Pakistan Stock Exchange (PSX). The PSX listing committee reviews applications and seeks public comments on the draft prospectus.
Companies and their consultants must address observations, update disclosures and submit a due diligence certificate. The PSX then decides on the listing application, followed by the SECP’s decision on the prospectus.
Once the prospectus is approved, it is published on the Public Offerings Revolutionized through an Integrated and Digitized Experience (PRIDE) platform, after which the book-building process begins.
SECP highlights criminal penalties and audit oversight
The SECP said Sections 134 and 136 of the Securities Act, 2015, make fraudulently inducing securities transactions and making false or misleading statements criminal offences.
The regulator also stressed the importance of accurate financial statements and reliable audits, saying they underpin fair stock prices, sound bank lending and accurate tax assessments. Misleading accounts can harm investors, lenders and government revenues.
The case has also highlighted the need to strengthen the Audit Oversight Board (AOB), the SECP said, calling for a legal framework aligned with international practices and the principles of the International Forum of Independent Audit Regulators (IFIAR).
The regulator said effective audit oversight requires the AOB to have sufficient inspection and enforcement powers, qualified technical staff and stable funding to hold auditors accountable.