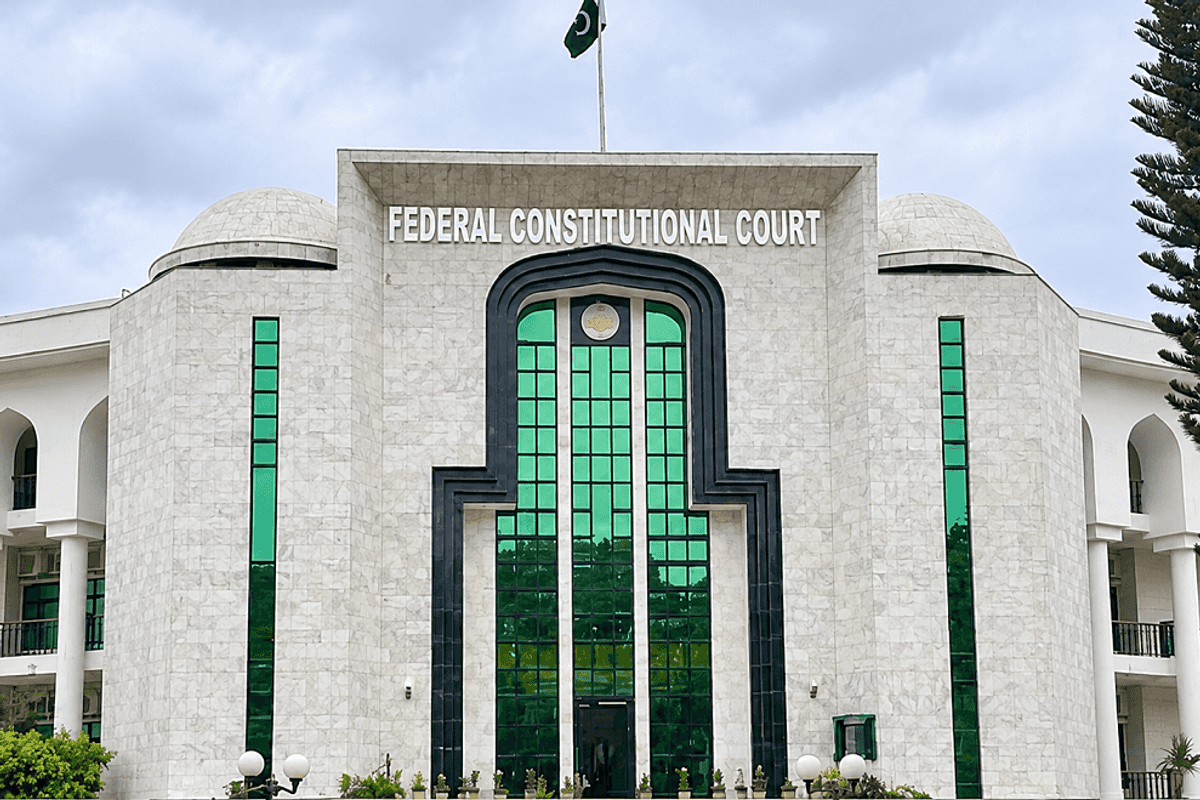
The court overturned earlier rulings of the Sindh High Court and Peshawar High Court that had upheld disputed infrastructure cess charges imposed by Sindh and Khyber Pakhtunkhwa.
In its detailed judgment, the court held that the challenged charges on imports, exports and goods in transit fell within federal legislative authority because of their customs-related nature.
It ruled that allocating revenue to provincial infrastructure development did not, by itself, establish the provinces' authority to impose such charges.
The court also declared related assessments and recovery measures unlawful, barring demands and penalties based solely on the invalid charges. Securities furnished against those charges are to be discharged following verification, subject to applicable court orders.
However, the judgment did not settle the constitutional validity of every possible provincial infrastructure charge, including certain purely domestic applications.
The SIDC has remained under litigation for nearly two decades. Introduced in 1994 at 1% of the cost-and-freight value of goods entering or leaving Sindh, the levy subsequently increased to 1.25% and then to 1.85% from July 2024.
In June 2021, the Sindh High Court upheld the 2017 Cess Act with retrospective effect. The Supreme Court suspended that ruling in September 2021 and allowed companies to clear goods against bank guarantees, prompting businesses to maintain provisions against potential liabilities.
Which companies could record the biggest earnings gains?
Topline Securities estimated that companies which had already entered settlement agreements previously carried approximately PKR 38.9 billion in SIDC liabilities and had recognized remeasurement gains of around PKR 16.9 billion.
The brokerage said the remaining provisions of approximately PKR 21.9 billion could now be reversed, subject to the legal and accounting implications of the ruling.
Honda Atlas Cars could record an earnings-per-share (EPS) benefit of PKR 13.92, followed by Indus Motor Company at PKR 12.87, International Steels at PKR 5.88, Engro Holdings at PKR 3.23 and Engro Fertilizers at PKR 1.82, according to Topline.
Other companies in its settlement group include Lucky Cement, Interloop and Cherat Cement.
In its corrected assessment, Topline identified approximately PKR 18 billion in liabilities among companies without settlement agreements, including Nishat Mills, Fauji Fertilizer Company, DG Khan Cement and Service Long March Tyres.
The brokerage estimated an EPS benefit of PKR 5.63 for Nishat Mills and PKR 4.92 for Fauji Fertilizer Company.
Topline's estimates cover a different group of companies from Arif Habib Ltd.'s assessment of approximately PKR 42.9 billion in cess-related liabilities across 11 listed firms.
However, the ruling is not expected to have a direct earnings impact on Pakistan State Oil, Wafi Energy Pakistan and Attock Petroleum, which have not recognized SIDC provisions in their financial statements, according to Topline.
What happens to previous settlements and payments?
In February 2026, Sindh reduced the cess to 0.85% for companies agreeing to withdraw litigation and settle outstanding dues, while companies without pending litigation were offered a rate of 0.80%.
Under the settlement arrangement, companies were required to pay 15% of their outstanding liabilities by July 15, 2026, another 15% by October 15, 2026, and a further 15% by July 15, 2027.
The remaining 55% was payable in 48 equal quarterly installments beginning July 15, 2028.
Arif Habib Ltd. said companies covered by its analysis had already booked approximately PKR 16.7 billion in one-off gains after remeasuring liabilities at present value under the settlement arrangement.
The brokerage also identified potential savings in financing costs. Its reported estimate indicates approximately PKR 5.15 billion in annual savings, assuming a 12% financing rate on the outstanding cess amounts.
However, payments already made under settlement agreements may not be recoverable. The 2026 amendment included a provision barring refunds or adjustments of amounts paid under those agreements.
The court's judgment also leaves individual disputes concerning payments, liabilities and refunds to the appropriate legal or administrative proceedings.
Companies will need to assess the implications of the ruling before reversing their outstanding provisions, particularly where settlement agreements have already been executed.
A potential review petition by provincial authorities could introduce further uncertainty over implementation.
The ruling could also have broader implications for provincial taxation, particularly levies linked to goods moving through Pakistan's ports and customs infrastructure.