SBP revises developer financing rules to expand housing supply
New developer financing rules require jointly operated escrow accounts, property valuation thresholds and six-monthly site inspections for housing lenders
Business Desk
The Business Desk tracks economic trends, market movements, and business developments, offering analysis of both local and global financial news.
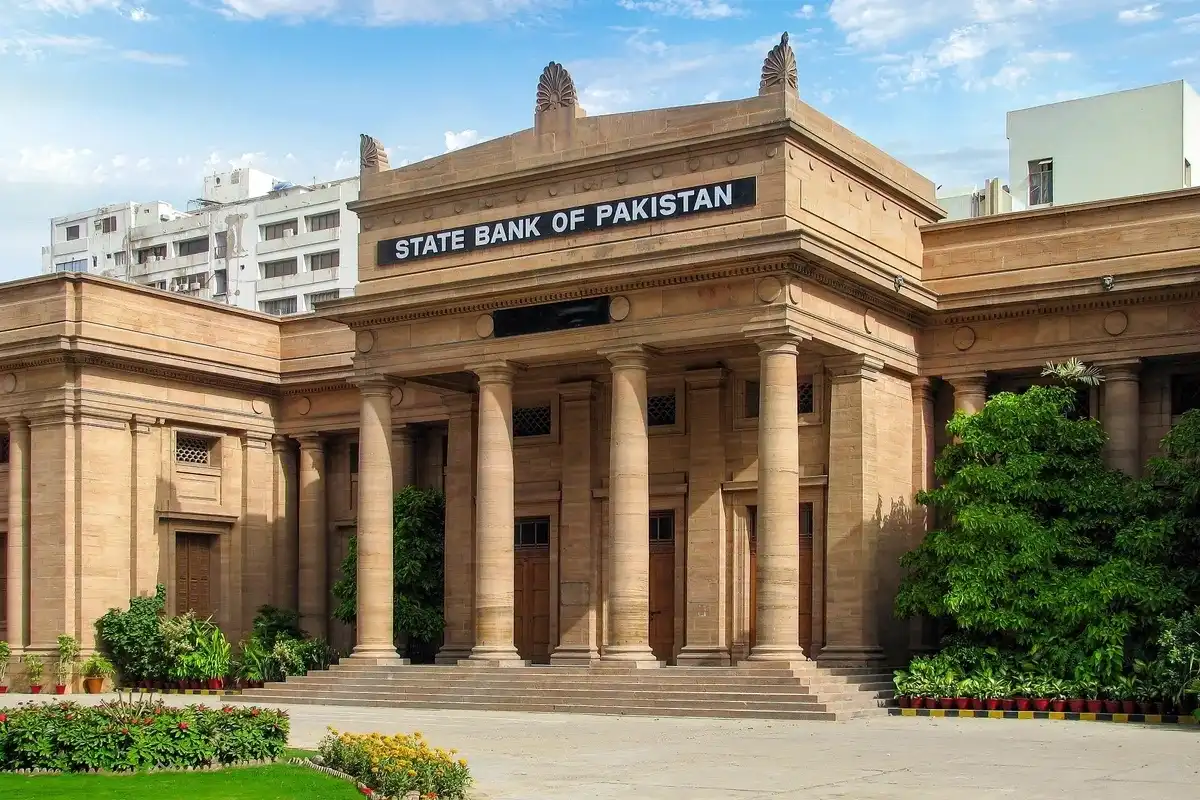
The State Bank of Pakistan (SBP) has revised financing guidelines for builders and developers to expand the supply of mortgageable housing units, requiring banks and development finance institutions (DFIs) to apply updated eligibility, valuation and project monitoring standards under a circular issued Wednesday, November 18.
What do the revised developer financing rules require?
The revised developer financing rules cover real estate investment trusts (REITs), public housing bodies, and private builders and developers. Applicants must satisfy licensing and land-ownership conditions, while lenders must assess financing risks. The guidelines also set valuation thresholds and require escrow accounts, project inspections and insurance coverage.
The framework updates guidelines issued in April 2014. Applicants need a valid builder or developer license where applicable, or an approved agreement with a competent public-sector authority. Private REITs, builders and developers must show a successful project completion record, and all applicants need clear, unencumbered title to the project land.
The SBP treats the land's value as equity contributed by the builder or sponsors.
Banks and DFIs may request registration records, three years of financial statements, tax documents and confidential banking reports. For financing up to PKR 500 million, those statements must be audited by a practicing chartered accountant or cost and management accountant. Above that threshold, the latest statements must be audited by an SBP-panel firm.
Lenders may also seek approved building plans, land titles, construction and sale permissions, and environmental clearances. Projects require independent technical feasibility reviews and endorsed financial feasibility reports.
How will banks value and monitor housing projects?
Financing up to PKR 50 million can use a desktop valuation by the lender. Amounts above PKR 50 million and up to PKR 500 million require at least one Pakistan Banks' Association-approved valuer, while financing above PKR 500 million requires at least two.
Lenders must obtain legal opinions and normally secure financing through a mortgage over the construction plot. Alternative property or guarantees may be accepted in specified circumstances.
During construction, banks and DFIs must review project accounts, check financial covenants and inspect sites at least once every six months. Technical consultants must also monitor progress, with financing drawdowns linked to their certification.
A jointly operated escrow account is mandatory, with booking payments, buyer installments and construction-related disbursements routed through it. All payments must be made by crossed cheques. Developers must maintain comprehensive construction insurance or takaful, with policies assigned to the lenders.
Approved layout plans and completion timelines must be publicly disclosed before bookings or allotments. Lenders must secure loans through assignments of project receivables, while financing agreements must provide for liquidation or sale to another developer after default, subject to legal formalities.
Comments
See what people are discussing