Thar coal switch could lift Lucky Electric dispatch, earnings: Arif Habib
SECMC’s Phase III expansion could lower LEPCL’s generation cost, boost plant utilization and raise returns for investors in the power plant and coal mine
Business Desk
The Business Desk tracks economic trends, market movements, and business developments, offering analysis of both local and global financial news.
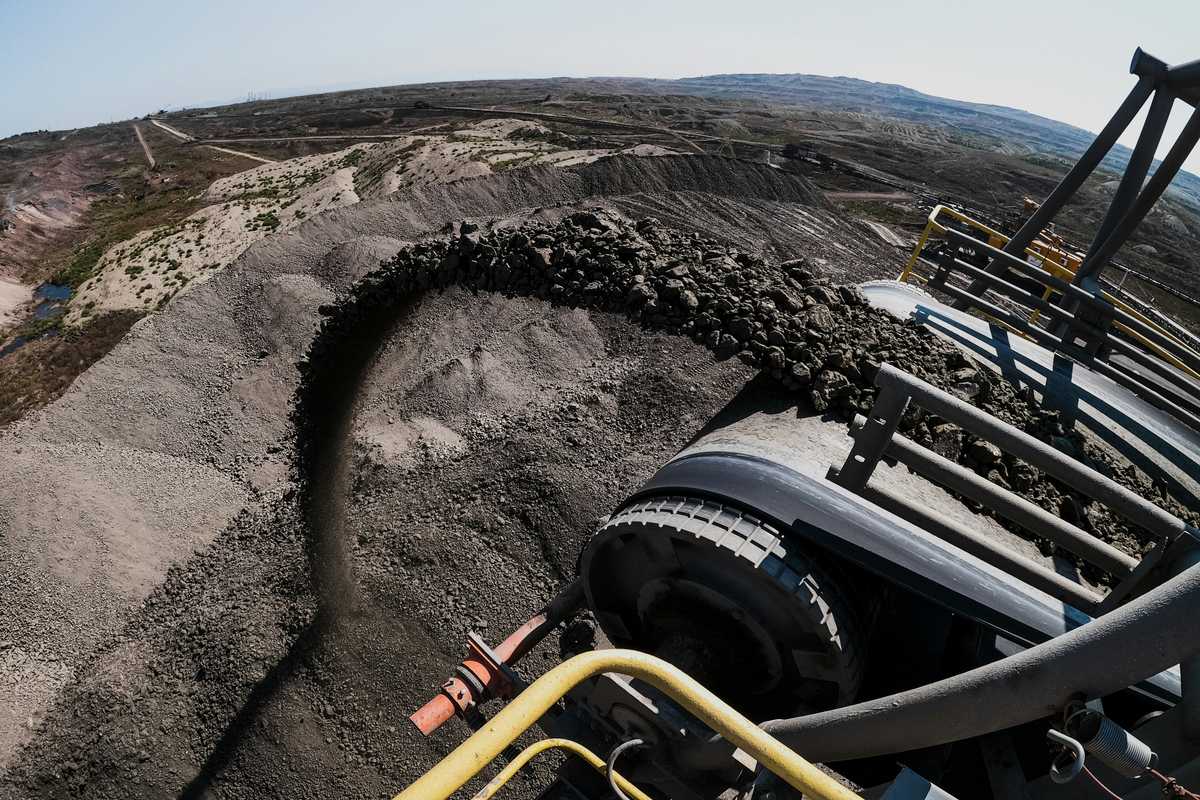
Additional coal supply is expected to enable LEPCL to fully switch from imported coal to Thar coal
Unsplash
The conversion of Lucky Electric Power Co. to locally sourced Thar coal is expected to significantly improve the power plant’s dispatch and earnings while boosting returns for its sponsors, according to a report by Arif Habib Ltd.
Sindh Engro Coal Mining Co.’s Phase III expansion of its Thar Block-II mine, inaugurated on October 5, raises annual production capacity to 11.2 million tons from 7.6 million tons. The report said the additional 3.6 million tons of coal will be supplied annually to LEPCL’s 660-megawatt power plant.
The additional coal supply is expected to enable LEPCL to fully switch from imported coal to Thar coal, potentially increasing the plant’s utilization to 60%-65% from about 37% currently, subject to electricity demand and transmission constraints, Arif Habib said.
SECMC was established in 2009 as a public-private partnership and operates the 95.5-square-kilometer Thar Block-II coalfield. The Sindh government holds 54.7% of its ordinary shares, with the remainder held by Engro Energy, Thal Ltd., Habib Bank Ltd., Hub Power Co. and CMEC Thar Mining Investments.
The mine’s Phase I, with capacity of 3.8 million tons per year, commenced commercial operations in July 2019, while Phase II raised capacity to 7.6 million tons per year and achieved commercial operations in October 2022.
Why does Thar coal give Lucky Electric a cost advantage?
Arif Habib said Thar coal gives LEPCL a major cost advantage over imported coal. The report estimates the switch could reduce the plant’s variable generation cost by about PKR 6.9 per kilowatt-hour before transportation costs, improving its position in the merit order and supporting higher dispatch.
The report cited the latest National Electric Power Regulatory Authority merit order as showing specific generation costs of about PKR 5.39-PKR 5.83/kWh for Thar-based plants, compared with PKR 12.75/kWh for LEPCL when operating on imported coal.
“LEPCL’s shift to locally sourced Thar coal should materially improve its dispatch economics,” the report said.
The cost advantage is already reflected in plant utilization. Thar-based plants including Engro Powergen Thar Ltd., Thar Energy Ltd., Thar Coal Block-I Power Generation Co. and ThalNova Power Thar Ltd. operated at roughly 70%-80% utilization in fiscal 2026, compared with 11% for China Power Hub Generation Co., 31% for Port Qasim Electric Power Co. and 36% for LEPCL, according to the report.
Arif Habib said LEPCL’s conversion should allow the plant to move higher in the merit order and increase dispatch, although north-south transmission constraints could continue to limit the evacuation of cheaper generation from southern Pakistan to northern load centers.
LEPCL’s regulated return to rise
The conversion is also expected to increase LEPCL’s regulated return on equity to 29.5% from 27.2%, with the ROE per unit of electricity rising to PKR 1.289 from PKR 1.188, the report said.
Based on Arif Habib’s estimates, the higher regulated return would generate an incremental PKR 1.55 billion in ROE for LEPCL in fiscal 2027, rising to PKR 1.80 billion by fiscal 2030.
For Lucky Cement Ltd., the benefit would translate into incremental earnings of PKR 1.06-PKR 1.23 per share, according to the report.
Arif Habib’s estimate uses a LEPCL project cost of USD 956 million, comprising 75% debt of USD 717 million and 25% equity of USD 239 million.
The higher ROE reflects additional returns allowed on the expanded project investment and is expected to provide a recurring earnings benefit rather than a one-time gain, Arif Habib said.
SECMC return on equity set for 51% jump
The Phase III expansion is also expected to materially increase SECMC’s return on equity.
According to the report, SECMC’s ROE is projected to rise to PKR 17.27 billion in fiscal 2027 from PKR 11.45 billion, an increase of PKR 5.82 billion, or about 51%.
The incremental ROE is expected to reach PKR 6.77 billion by fiscal 2030 as the expanded mine operates at higher capacity.
For Hub Power Co., or HUBCO, the additional ROE contribution is estimated at PKR 465 million in fiscal 2027, rising to PKR 541 million by fiscal 2030. That would translate into incremental earnings of PKR 0.36-PKR 0.42 per share.
For Engro Holdings, the incremental ROE contribution is estimated at PKR 692 million in fiscal 2027, increasing to PKR 805 million by fiscal 2030, equivalent to PKR 0.57-PKR 0.67 per share, according to the report.
The expansion is supported by a coal supply agreement between SECMC and LEPCL and is expected to strengthen the economics of both the mining operation and the power plant by replacing expensive imported coal with cheaper domestic fuel.
Comments
See what people are discussing