Pakistan's GDP growth to reach 3.8% in FY27 amid Middle East conflict: World Bank
Inflation is projected to rise to 8.2% as elevated energy prices and weather-related risks weigh on Pakistan's economic recovery
Business Desk
The Business Desk tracks economic trends, market movements, and business developments, offering analysis of both local and global financial news.
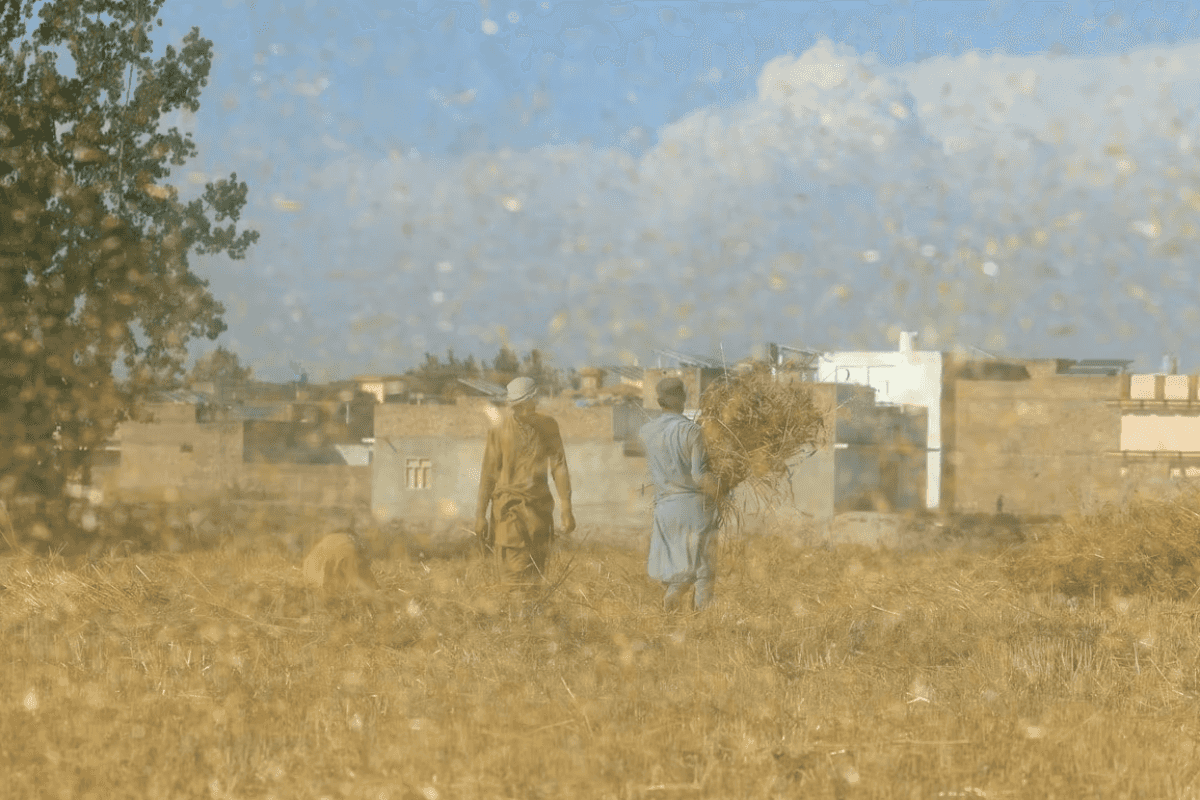
Laborers work in a wheat field in Peshawar, May 4, 2026.
Reuters
- Pakistan's current account deficit is projected to widen to 0.8% of GDP in FY27.
- Strong remittances are expected to finance most of the trade deficit.
- El Nino and higher fertilizer costs are expected to weigh on crop production.
- Economic growth is projected to gradually reach 4.5% by FY31.
Pakistan's economy is projected to grow 3.8% in fiscal year 2027 (FY27), up slightly from an estimated 3.7% in FY26, as the conflict in the Middle East, elevated commodity prices and unfavorable weather conditions constrain the country's recovery, according to the World Bank.
In its latest Pakistan Development Update: Attaining Escape Velocity, the bank said economic growth would strengthen gradually over the medium term as commodity prices normalize, inflation eases and agricultural input costs decline.
Gross domestic product (GDP) growth is projected to reach around 4.5% by FY31.
What is weighing on Pakistan's economic outlook?
The World Bank expects the Middle East conflict to keep energy and commodity prices elevated, limiting economic growth in FY27. Higher fuel costs are also expected to contribute to inflation, while unfavorable El Nino weather conditions and expensive fertilizers could constrain crop production, slowing the broader economic recovery.
Under the bank's baseline scenario, energy and commodity prices are expected to return to pre-conflict levels only in the second half of FY27.
Headline inflation is projected to rise to 8.2% in FY27 from 7.1% in FY26, reflecting elevated global commodity prices and domestic food price pressures.
Higher energy costs are expected to feed into transportation costs and core inflation during the first half of FY27. Food inflation is also expected to remain elevated due to wheat and perishable commodity prices, with El Nino-related disruptions posing additional risks.
However, favorable base effects in the fourth quarter of FY27, moderate domestic demand under continued fiscal consolidation and improved wheat availability are expected to gradually ease inflation.
Inflation is projected to decline to 7% in FY28 before rising to 7.5% in FY29 ahead of the general election scheduled for 2029. It is expected to stabilize at around 7% in FY30.
Agriculture and industry face mixed prospects
Agriculture is expected to remain vulnerable to unfavorable weather conditions and higher input costs, particularly fertilizer prices during the Rabi season.
Livestock is projected to remain the main driver of agricultural growth, while crop production is expected to recover gradually.
The World Bank cautioned that its baseline projections do not account for more severe El Nino outcomes, including droughts or other extreme weather events, which could further reduce agricultural output.
Industrial activity is expected to strengthen marginally in FY27, supported by manufacturing and construction. Construction is expected to benefit from lower property taxes introduced in the FY27 budget, the report said.
Services sector growth is projected to remain broadly unchanged from FY26 as a slow agricultural recovery and elevated inflation constrain wholesale and retail trade.
Over the medium term, lower commodity prices and easing inflation are expected to support a broader recovery.
Manufacturing and construction are projected to strengthen further, while services will remain the largest contributor to economic growth.
The contribution of information and communications technology (ICT) services is also expected to increase, although from a relatively low base.
Current account deficit expected to widen
Pakistan's current account deficit is projected to widen in FY27 as recovering domestic demand pushes imports higher, with imports expected to grow faster than exports, the World Bank said.
Merchandise exports are expected to recover modestly alongside improving industrial activity, while ICT services exports are projected to continue expanding.
Strong workers' remittances are expected to finance most of the trade deficit, helping keep the current account deficit below 1% of GDP.
The report projects a current account deficit of 0.8% of GDP in FY27, compared with 0.1% in FY26.
Official financing and renewed access to international capital markets are expected to keep Pakistan's financial account in surplus, while potential additional investment inflows could provide further support.
Pakistan's return to international bond markets is expected to broaden its financing options, although the external outlook remains sensitive to global commodity prices, trade performance and the availability of financing.
Fiscal outlook and risks
The World Bank's baseline outlook assumes continued sound macroeconomic policies without additional major structural reforms.
It also assumes fiscal loosening ahead of the 2029 general election will be more limited than during previous election periods.
The primary fiscal surplus is projected to narrow from 2.9% of GDP in FY26 to 2% in FY27, while the overall fiscal deficit is expected to widen from 2.6% to 3.5% of GDP.
The bank warned that a more prolonged or intense Middle East conflict remained the biggest near-term risk to Pakistan's economy, potentially increasing import costs, weakening export demand and putting further pressure on inflation and foreign exchange reserves.
Severe El Nino-related disruptions could also weaken agricultural production and slow economic growth.
While moderating inflation and lower agricultural input costs are expected to support the recovery over the medium term, the outlook remains dependent on global energy prices, weather conditions and the strength of domestic demand.
Comments
See what people are discussing