Pakistan stocks could return 25% by December 2027, Topline says
Pakistan stocks could return 25% by December 2027 as the KSE-100 targets 220,000 points, Topline says, citing easing inflation and stronger external finances
Haris Zamir
Business Editor
Experience of almost 33 years where started the journey of financial journalism from Business Recorder in 1992. From 2006 onwards attached with Television Media worked at Sun Tv, Dawn Tv, Geo Tv and Dunya Tv. During the period also worked as a stringer for Bloomberg for seven years and Dow Jones for five years. Also wrote articles for several highly acclaimed periodicals like the Newsline, Pakistan Gulf Economist and Money Matters (The News publications)
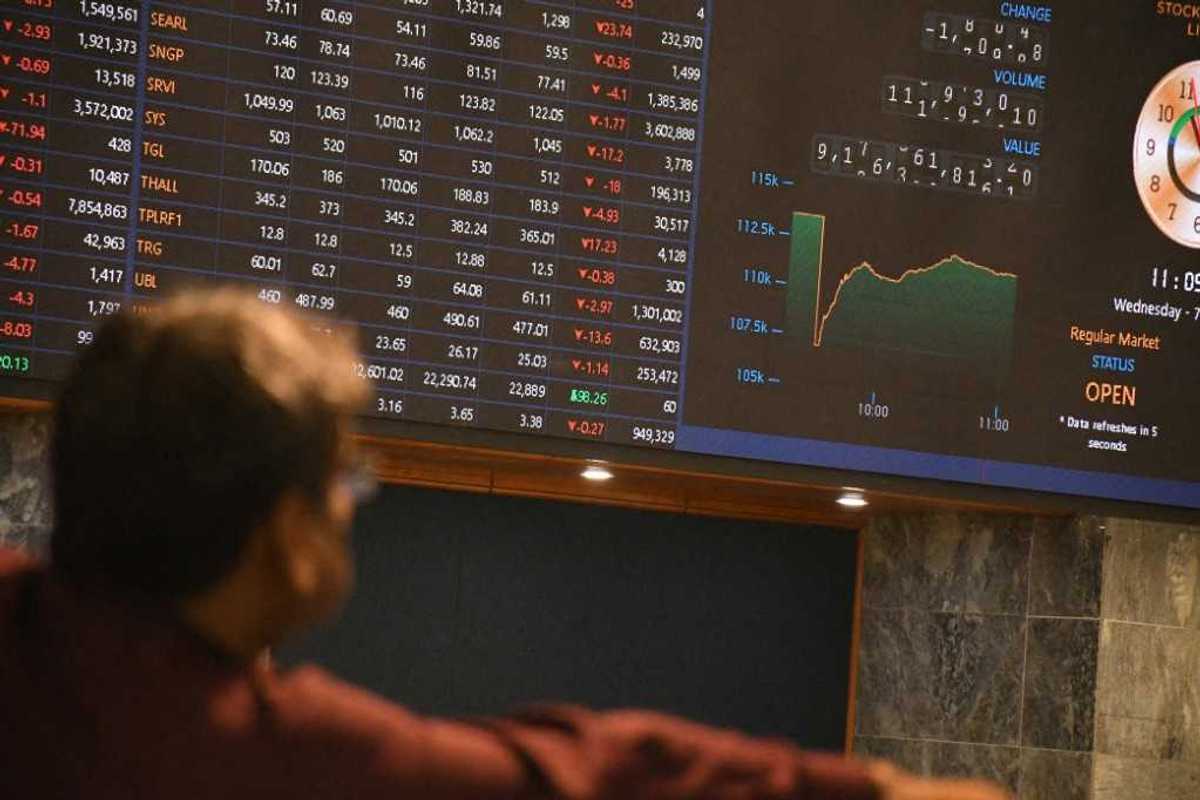
Pakistan stocks could deliver an estimated total return of 25% by December 2027, including a 7% dividend yield, with the benchmark KSE-100 index projected to reach 220,000 points, Topline Securities said in its Pakistan Market Outlook 2027.
The brokerage cited easing inflation, lower borrowing costs and stronger external finances.
How did Topline set its target for Pakistan stocks?
Topline's target rests on a forward price-to-earnings (P/E) multiple of seven times for 2027. That compares with historical averages of 7.3 times when economic growth exceeded 3.5% and 6.7 times when foreign exchange reserves covered more than three months of imports.
Topline expects Pakistan's economy to expand by 3.5% to 4% in fiscal year 2027, compared with 3.7% in FY26, before growth accelerates to 4% to 4.5% in FY28. It said the conflict involving Iran had disrupted the country's economic recovery, although Pakistan had shown resilience during the crisis.
What could move Pakistan stocks in 2027?
Topline identified international oil prices, particularly developments involving the United States and Iran and shipping through the Strait of Hormuz, as the biggest external variable for Pakistan's economy and financial markets next year. Other factors likely to shape investor sentiment include the progress of the International Monetary Fund (IMF) programme, external financing, foreign exchange reserves, sovereign credit rating upgrades, potential tax relief in the FY28 budget, circular debt resolution and privatisation.
Domestic investors have remained the main source of buying at the Pakistan Stock Exchange, offsetting foreign selling, the brokerage said. A relatively stable rupee, reduced investment appeal of Dubai and expectations of lower interest rates in the second half of 2027 could further support local equities. Political uncertainty and security concerns remain key downside risks.
Why are oil prices the biggest external risk?
Pakistan's exposure to the Middle East makes energy prices a critical determinant of its economic outlook. Before the conflict, around 90% of the country's oil imports originated from the Gulf, while it also depended on liquefied natural gas supplies from Qatar, Topline said.
Disruptions to shipping through the Strait of Hormuz, which handled about 20 million barrels of oil a day, or roughly one-fifth of global consumption, before the conflict, have pushed up transportation and insurance costs and affected supply chains. The brokerage said the Brent-Dubai crude oil price spread widened to a record $22.20 per barrel in mid-September 2026, compared with less than $2 during the preceding two years.
Topline has assumed an average Brent crude price of $86 per barrel in 2027, down from $91 in 2026 to date, based on the US Energy Information Administration's outlook. Every $10-per-barrel increase in oil prices could add 35 to 40 basis points to Pakistan's consumer inflation and widen its annual current account deficit by $1.6 billion to $2 billion, equivalent to about 0.4% of gross domestic product, it estimated.
A fresh escalation that pushes Brent above $110 per barrel could keep inflation in double digits and delay monetary easing until FY28.
What is the outlook for inflation and interest rates?
Topline expects average inflation to reach 9.5% to 10.5% in FY27 before easing to 7% to 8% in FY28, supported by moderating oil prices and favourable base effects from April 2027. Annual inflation fell to 9.6% in October 2026 from 10.3% in September.
The brokerage expects inflation to remain between 10% and 11% through March 2027 before declining to 8.5% to 9.5% in April and May. The State Bank of Pakistan (SBP) is projected to hold its policy rate at 12% through June 2027 before delivering a 100-basis-point cut in the second half of the year, bringing it to 11% by December.
The central bank has raised borrowing costs by a cumulative 150 basis points in 2026, including increases of 100 basis points in April and 50 basis points in October. A lower interest rate environment could benefit leveraged and rate-sensitive industries, particularly cement, automobiles and consumer businesses, while potentially squeezing banks' margins. Cheaper borrowing costs could also encourage private-sector credit growth.
How strong are Pakistan's external finances?
Pakistan entered the latest energy crisis with stronger economic safeguards than during the 2022 oil shock, including higher foreign exchange reserves, a relatively balanced current account and an ongoing IMF programme, Topline said. The current account deficit was just $100 million, equivalent to 0.03% of GDP, in FY26, when economic growth reached 3.7%.
The brokerage expects the deficit to widen to $2.8 billion, or 0.55% of GDP, in FY27 as imports increase by 12%, driven largely by petroleum purchases. Remittances from overseas Pakistanis are projected to reach $44.9 billion, helping offset the higher import bill.
SBP foreign exchange reserves are expected to rise to $24.9 billion by June 2027, providing about four months of import cover and broadly meeting the central bank's $25 billion target. Liquid foreign exchange reserves increased to $21.5 billion in October 2026 from $14.5 billion in June 2025, equivalent to 3.6 months of import cover, according to Topline.
The improvement has also been supported by the central bank's foreign exchange purchases rather than relying entirely on additional external borrowing. The SBP has reduced its forward liabilities from more than $5.7 billion to less than $1 billion, the brokerage said.
Pakistan's external debt servicing requirements are estimated at $21.5 billion in FY27, down from $26.5 billion in FY26. Around $10.5 billion is expected to be rolled over or refinanced, leaving net repayments of approximately $11 billion.
To meet its financing needs, the brokerage expects Pakistan to raise another $1 billion to $1.5 billion through Sukuk, a second tranche of Panda bonds and commercial borrowing during 2027. Meanwhile, the fiscal deficit is projected to widen to 3.5% of GDP in FY27 from 2.6% in FY26. Pakistan recorded a primary surplus of 2.9% of GDP in the previous fiscal year.
What role will the IMF program and policy reforms play?
The IMF programme will remain central to Pakistan's macroeconomic stability and access to external financing, Topline said. A staff-level agreement on the fourth review of the $7 billion Extended Fund Facility (EFF) and the $1.4 billion Resilience and Sustainability Facility (RSF) was reached in October 2026.
The agreement paved the way for disbursements of $1.2 billion, taking total payments under the programmes to about $5.7 billion. With two reviews and approximately $2.7 billion in funding remaining, timely completion of the programme will be important for meeting the country's foreign exchange reserve targets, the brokerage said.
It also raised the possibility of another IMF arrangement after the current programme expires in October 2027, citing growing external financing requirements. Pakistan's gross external financing needs are projected to rise from $18.8 billion in FY26 to $21.2 billion in FY27 before reaching $29.9 billion in FY28.
Government policies targeting specific industries could also provide investment opportunities. The Brownfield Refinery Policy, notified in September 2026, envisages investments of $5 billion to $6 billion over the next five to six years to upgrade refineries to Euro-V standards.
The Auto Policy 2026-31 seeks to encourage new energy vehicles, improve affordability, boost exports and increase local manufacturing. Proposed incentives include a 1% sales tax on electric vehicles and gradual reductions in duties on completely knocked-down vehicle imports.
Topline also sees the proposed minerals policy as a potential avenue for attracting foreign investment. However, security concerns, higher capital costs and execution challenges have slowed progress on the Reko Diq project. Further progress on the privatisation of electricity distribution companies, following the sale of Pakistan International Airlines, could also improve investor confidence, it said.
Which sectors and stocks does Topline prefer for 2027?
For 2027, Topline has an overweight position on banks, cement, pharmaceuticals, exploration and production companies, and automobiles. Lower interest rates are expected to support cement and automobile manufacturers, while banks and fertiliser companies could remain attractive because of their dividend yields.
The brokerage also expects a possible recovery in industries that underperformed in 2025 and 2026, particularly pharmaceuticals. Its 10 preferred stocks for 2027 are Oil and Gas Development Company, United Bank Ltd., Meezan Bank Ltd., Fauji Fertilizer Company, Engro Holdings, Maple Leaf Cement Factory, Attock Refinery, Sazgar Engineering Works, Hub Power Company and GlaxoSmithKline Pakistan.
For its Alpha stock portfolio, Topline favours Atlas Honda, Ghandhara Industries, Pakistan Tobacco Company and Adamjee Insurance Company.
Overall, improving macroeconomic stability, moderating inflation, potential interest rate cuts and industry-specific reforms could support Pakistan's equity market in 2027. However, international oil prices, geopolitical tensions and domestic political and security challenges remain important risks to the outlook, the brokerage said.
Comments
See what people are discussing